Ownership Program
Ownership Program
Liberty Home Ownership is a down payment assistance program. We know that a major obstacle to home ownership for many hard-working Albertans is coming up with the down payment to purchase their own home.
Our goal is to clear this obstacle through our innovative shared equity model. You contribute just $1,500 and Liberty provides the remainder of the required 5% down payment.
This program may be a fit for you if:
- You are able to apply and successfully qualify for mortgage approval with one of our approved lending partners.
- You have permanent, steady employment and are able to contribute just $1,500 of your own funds to go towards a required 5% down payment.
- The home you choose with Liberty will be your permanent sole residence. The home cannot be purchased for investment/rental purposes.

A fair exchange, explained upfront.
Liberty’s contribution is not a conventional dollar-for-dollar down-payment loan. If you later sell, refinance or trigger another transaction defined as a Disposition in your agreement, the contract-defined Shared Equity Amount is divided under a time-based schedule. Your share increases with time.
Could Liberty be your way in?
Answer four quick questions to see whether the program may fit. This is not a mortgage application and will not affect your credit.
Step 1 of 4
Liberty may be worth exploring.
Your answers suggest Liberty may be a potential fit. The next step is a conversation about the program and mortgage qualification.
Mortgage and program approval, participating home availability, and full program terms still apply.
Next steps:
Choose the option that fits you best.
Let’s talk about
your next step.
Not meeting every criterion today doesn’t mean the conversation has to end. Our team would be happy to explain the requirements and discuss what you may need to work toward before applying.
Unsure about mortgage readiness? We can help you connect with an approved lending partner to explore your circumstances.
Next steps:
Choose the option that fits you best.
A conversation does not guarantee eligibility or mortgage approval.
How Liberty Works
From your first question to the keys in your hand – here is how the Liberty Home Ownership program works.
Qualify
Qualified buyers must make $75k/year and be able to apply and successfully qualify for a mortgage approval
Approval
For eligible buyers, Liberty may contribute a shared-equity amount toward the purchase. Covering the necessary 5% down payment.
Choose
Review current eligible home and select the right fit for your approved range.
Own
Contribute $1,500 down toward the required 5% down payment. Liberty provides the balance through a shared-equity arrangement.
A different path to owning - and building value
Liberty offers a more flexible and equitable path to homeownership compared to traditional fixed-price, restricted-resale programs. Here’s how we stack up:
Liberty vs Other Programs
Your Contribution
Liberty starts with $1,500 toward the 5% down payment. Others may require a higher minimum.
Building Equity
Liberty lets you pay down your mortgage and keep your applicable share of market appreciation.
Some fixed-price models allow principal repayment but no market appreciation.
Selling
Liberty lets you sell on the open market (subject to agreement). Other programs require resale to the program.
Resale Price
Liberty’s price reflects the market when you sell. Some program resale prices are fixed or controlled.
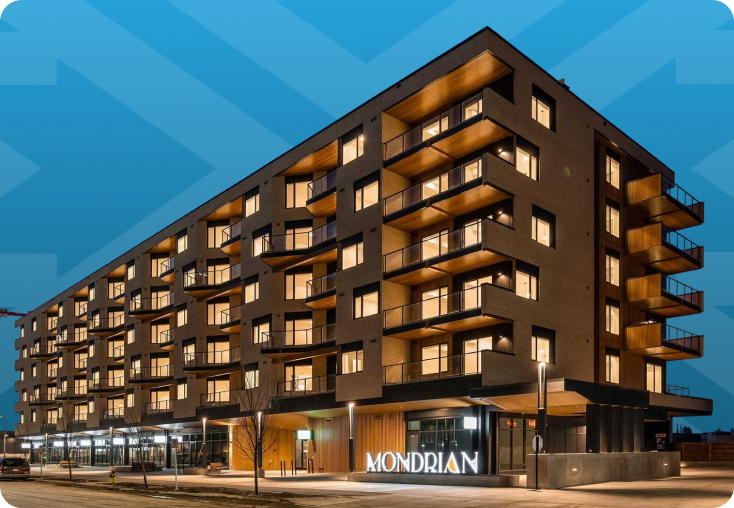
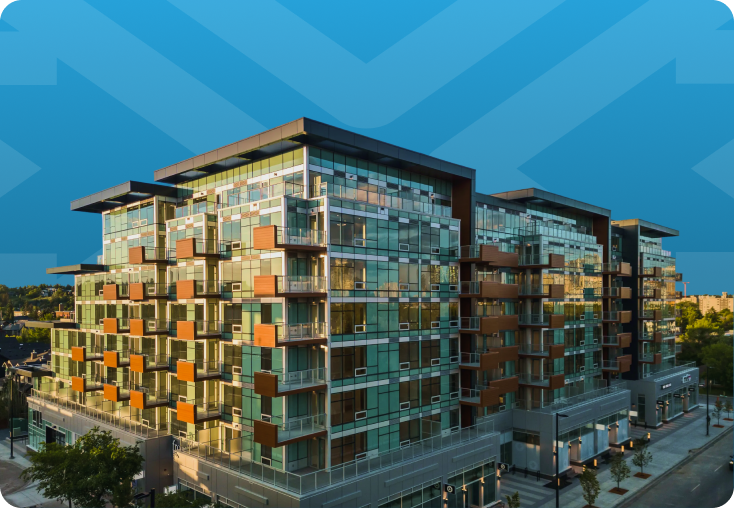
Available Homes
Shared Equity Explained
Liberty helps complete the required 5% down payment. If a contract-defined Disposition later occurs, the Shared Equity Amount is divided under a time-based schedule. The longer you own, the more of that amount you keep.
Year 1
0
%
Vendor receives 90% of the Shared Equity Amount or the full Forgivable Equity Loan, whichever is greater.
Year 1-2
0
%
30% to purchaser / 70% to Vendor.
Year 2-3
0
%
60% to purchaser / 40% to vendor.
Year 3-20
0
%
80% to purchaser / 20% to Vendor. Your share increases with time.
Get-Pre Qualifed
Obtain your mortgage pre-approval: we automatically pair you up with our partner financial institution to determine your eligibility..
Alicia Deloughery
Mortage Specialist
Alicia.Deloughery@servus.ca
403.830.6593
FAQ
Answering your frequently asked questions
Liberty’s Affordable Home Ownership Program was created in 2015 to address the growing housing affordability gap in Canada. Our 3 key factors that make home ownership a practical reality for Albertans:
Attractive home prices
Forgivable equity loans
A shared appreciation plan that provides a financial stake in equity for customers in the purchase of their new home
You will notice that Liberty does not have a minimum credit score required to be a part of our program, but you have to qualify for a mortgage. Liberty Housing Organization helps gives you a down payment, but the mortgage approval process is exactly the same as it would be for any other purchase.
One of the main things lenders consider when applying for a mortgage is your credit score. A credit score is a number assigned to a person that indicates to the lender or bank their capacity to repay a loan. In short, a credit score shows lenders the level of risk associated with lending you money.
In Canada, credit scores will generally range from 300 – 900 (900 being the highest). If your score is 650 and above, you shouldn’t have an issue being approved for a mortgage through most lenders. In some cases, people with a credit score of 600 and above may get approved, but a history of debt repayment would be important to demonstrate your understanding of financial responsibility.
If you’d like to purchase through Liberty’s Home Ownership Program, you will have to qualify for a mortgage. Unfortunately, most major lenders, including our lender partners, will not grant mortgages to people in consumer proposal.
If you are in consumer proposal, we hope you’ll revisit the program once the proposal has been completed.
Liberty was created to help moderate-income Albertans with steady employment who have been held back from home ownership. No matter the job, trade, or profession, Liberty can assist in achieving the goal of home ownership.
Housing prices have been increasing at a much faster pace than the average Albertan’s salary, locking many hard-working people out of the ownership market. Many of our customers have sufficient income to manage mortgage payments, but still have been unable to save a down payment as a result of increasing rent and cost of living.
In being a non-profit organization, it’s the support we receive from our building and development partners that enables us to offer attainable pricing for our homes. This is done by our partners reducing the purchase price from the fair market value of the home, which typically results in a discount up to 15% substantiated by an independent third-party appraisal of the homes Liberty seeks to acquire.
If you’d like to purchase through Liberty’s Home Ownership Program, you will have to qualify for a mortgage. Unfortunately, most major lenders, including our lender partners, will not grant mortgages to people until your bankruptcy no longer shows on the credit bureau.
We hope you’ll revisit the program once this happens.
To remove Liberty from your title, we would require the following information via email to sales@libertyhousingorganization.ca:
The original mortgage approval for your home.
A current home appraisal. You can find an appraiser here on the following website: https://www.aicanada.ca/need-an-appraiser/find-an-appraiser/
Once you have provided that information we will calculate your payout amount, which is either:
The shared equity amount, or
$8,000.00
(whichever is the greater value)
When we have calculated the payout amount, you can then get in touch with our solicitor.